Does Insurance Cover
Hearing Aids in New York?

The honest answer: it depends on your plan, not your insurance company’s logo. Two people with the same insurer can have completely different hearing benefits. Here is how coverage actually works in New York, and how to get a real answer for your plan.
The short answer: some New York plans cover hearing aids well, some offer a partial allowance, and some cover nothing, even within the same insurance brand. Coverage is set by your specific plan: the employer group, the product line, the county, and the year all matter. The only reliable answer comes from verifying your individual benefits, which we do for every patient before their visit.
Coverage by plan type
- Commercial and employer plans: many include a hearing aid allowance, commonly once every 3 to 5 years; union and municipal plans in New York are often among the more generous.
- Medicare Advantage (Part C): most plans add a hearing benefit, usually as copays or an allowance through a contracted network. Details vary enormously by plan and county.
- Original Medicare: does not cover hearing aids; Part B covers physician-ordered diagnostic testing. See our full Medicare guide.
- Medicaid and managed Medicaid in NY: hearing aids are covered for eligible members under specific rules and prior approvals.
- FSA / HSA: hearing aids and related care are eligible pre-tax expenses regardless of plan coverage.
UHC, Aetna, BCBS and the third-party benefit
Here is the part that surprises people: many insurers do not administer hearing benefits themselves. Instead they contract a third-party hearing program, such as UnitedHealthcare Hearing, TruHearing (common with Aetna and many Blue Cross Blue Shield plans), Amplifon, or NationsHearing. Your benefit may only apply when devices are ordered through that program’s catalog and network, which can limit brand and model selection and changes how pricing works. A "covered" hearing aid through a third-party program is sometimes a different model tier than the same name suggests at retail.
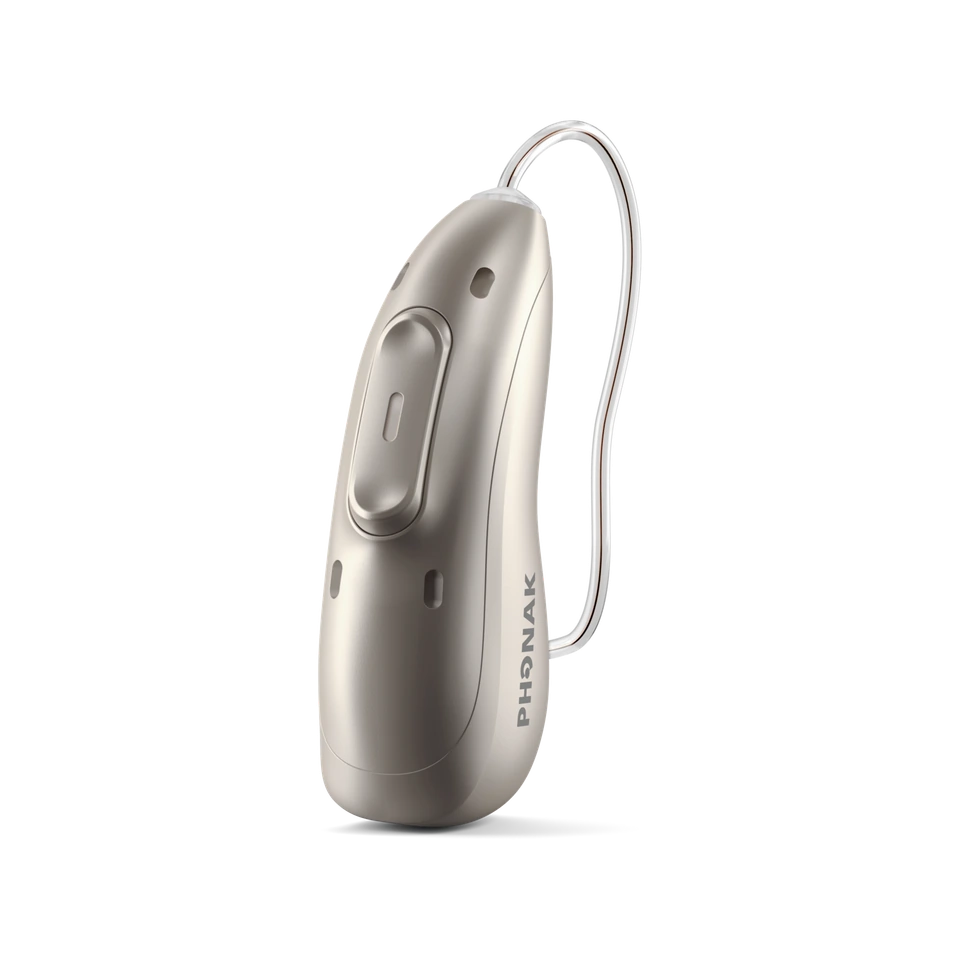
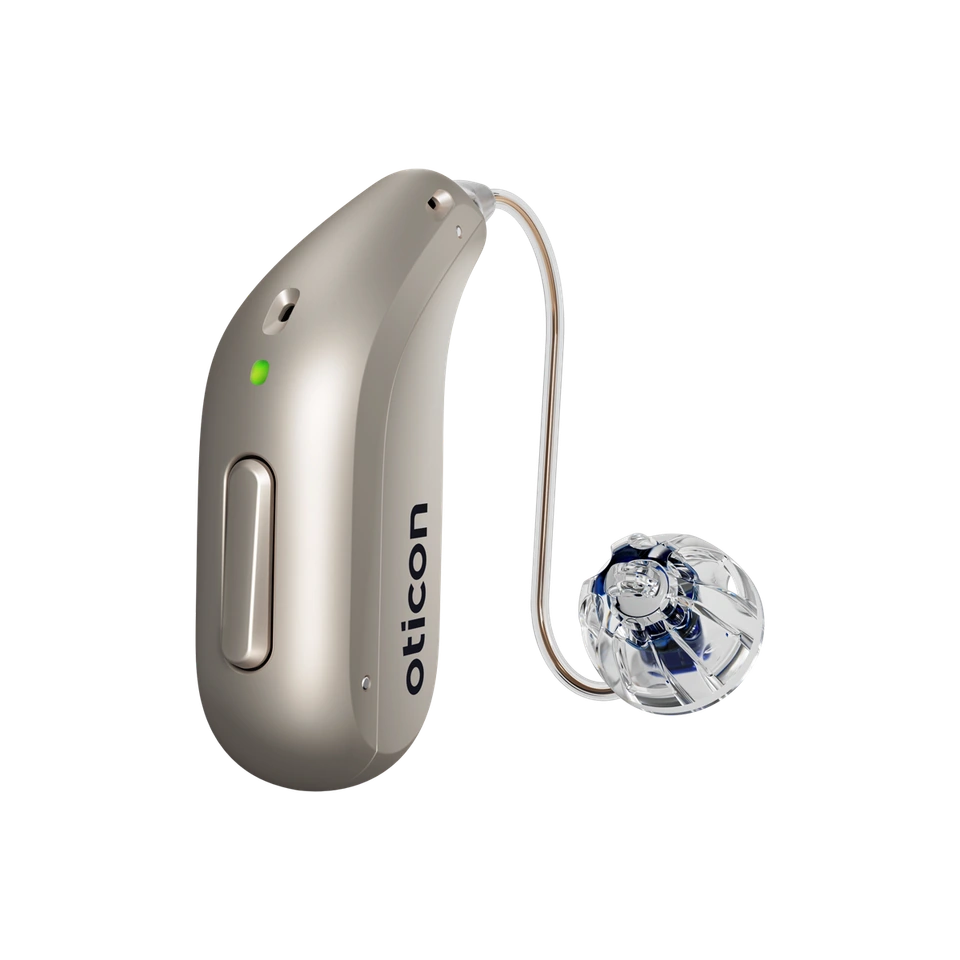
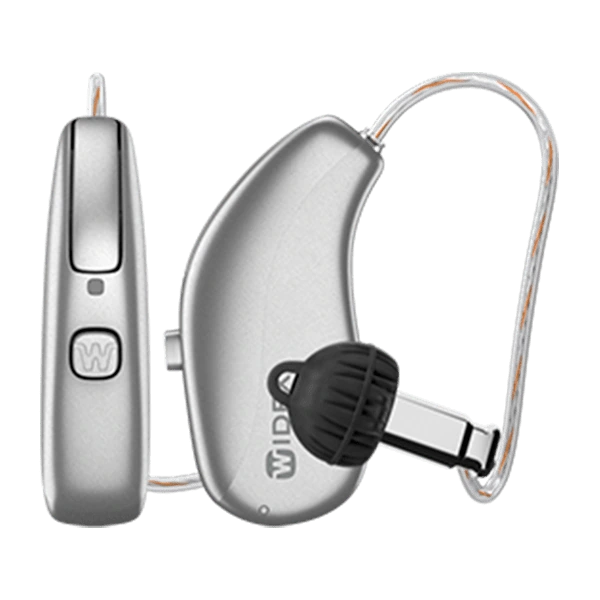
Hearing aids, up close
Official manufacturer images of prescription hearing-aid examples. These photographs identify the models shown, not a recommendation for your hearing or a guarantee of availability.
Terms worth knowing
- Allowance: a fixed dollar amount the plan contributes toward devices.
- Coinsurance: the percentage you pay after any deductible.
- Third-party hearing benefit: an outside program that administers the benefit on the insurer’s behalf.
- In-network vs. out-of-network: whether your provider participates in the plan or program; this can change both price and paperwork.
What to ask your insurance company
- "Does my plan include a hearing aid benefit, and is it an allowance or a copay?"
- "Is the benefit administered by a third party such as UHC Hearing, TruHearing, or NationsHearing?"
- "How often does the benefit renew, and does it cover fitting and follow-up visits?"
- "Is diagnostic hearing testing covered, and do I need a referral?"
Verify first, quote second. Real numbers beat brand-level promises.
How Pinnacle makes this simple
Call our team or request a callback before your visit so we can explain how to provide the information needed to verify your benefit: testing coverage, allowances, third-party programs, and renewal dates, so you see actual numbers before you commit. We are independent and brand-neutral, we work with most major insurers and hearing programs, and we explain trade-offs honestly, including when paying outside a third-party program gets you a better device for similar money. Start with our insurance and benefits page, compare typical price ranges in our hearing aid cost guide, or request an insurance callback for verification at our Midtown Manhattan or Garden City office.
Frequently asked questions
Does insurance cover hearing aids in New York?
Plan-dependent. Many commercial and Medicare Advantage plans contribute; Original Medicare does not. Verification gives the real answer.
Link to this answerWhat is a third-party hearing benefit?
An outside program (UHC Hearing, TruHearing, NationsHearing, Amplifon) that administers your hearing benefit, usually with its own network and catalog.
Link to this answerCan I use FSA or HSA funds?
Yes, hearing aids and related care are eligible pre-tax expenses.
Link to this answerDo you verify benefits before I come in?
Yes, for every patient. It is the only way to quote honestly.
Link to this answerHow we verify your benefits
Insurance language is deliberately hard to read, so we do the legwork for you. Before you commit to anything, we contact your plan and confirm the specifics that actually matter: whether diagnostic testing is covered, whether there is a hearing aid allowance or discount, which device tiers or providers qualify, and how often the benefit renews. You get a clear out-of-pocket number rather than a brochure estimate, which means no surprises at checkout.
Beyond the plan: FSA, HSA, and more
Even when a plan covers little, there are usually ways to soften the cost. Flexible spending and health savings accounts can typically be used for hearing aids and evaluations, spreading the expense pre-tax. Some patients qualify for help through specific programs, and financing can break the cost into manageable payments. We lay out every option that applies to you instead of steering you only toward what a plan happens to reimburse.
If a claim is denied
Denials are not always final. When testing is medically warranted, a denial can sometimes be appealed with the right documentation, and we help assemble what your plan needs. The goal is simple: get you the care you are entitled to with as little friction as possible. Our insurance and benefits page covers the plans we work with.
How verification works, step by step
Here is exactly what happens after you call our team or request a callback before a visit. First, we confirm your plan is active and identify whether hearing benefits are handled in-house or by a third-party program. Second, we verify diagnostic testing coverage, so you know what the evaluation itself will cost. Third, we confirm the device benefit: allowance amount or copay structure, which technology tiers qualify, network requirements, and when the benefit last renewed. Finally, you get real numbers in writing before you make any decision. The whole process usually takes a day or two, and it costs you nothing.
Using a third-party benefit vs paying directly
When your benefit runs through a program like TruHearing or UnitedHealthcare Hearing, the covered devices come from that program’s catalog, and the service model, how many follow-ups, who does the fitting, what happens after the first year, is defined by the program rather than your audiologist. As the National Council on Aging notes, these benefits are often structured as allowances or discount access rather than full coverage.
Sometimes the third-party route is clearly the right value. Sometimes, especially for complex losses or patients who want long-term care from one clinician, paying directly for a device with bundled service costs a similar amount over five years and delivers more. We lay out both paths with real numbers and let you choose; that comparison is only possible when your benefits have actually been verified.
New York notes: Medicaid, unions, and timing
A few local specifics worth knowing. New York Medicaid and managed Medicaid plans cover hearing aids for eligible members under specific rules and prior-approval requirements; if you are dual-eligible for Medicare and Medicaid, coverage can combine in your favor. Union and municipal benefit funds in New York, including many city and state employee plans, often carry hearing allowances that members do not realize they have; retirees frequently keep them. And if you hold an FSA, remember balances generally expire at year end, which makes late-year evaluations a smart move. Questions about a specific plan are answered fastest through our insurance page or a quick call to the office.
Testing coverage and device coverage are different things
One distinction resolves half the confusion we see: your plan’s coverage for the hearing evaluation and its benefit for hearing aids are separate provisions that behave separately. Diagnostic testing is medical care, and most plans cover it like any specialist visit, sometimes requiring a referral. The device benefit, when one exists, is usually a distinct allowance with its own rules, network, and renewal clock. It is entirely common to have excellent testing coverage and no device benefit, or the reverse. When we verify your benefits, we check both, so the evaluation and any devices that follow are each quoted accurately.
Three myths that cost people money
"My insurance brand covers hearing aids." Coverage is set at the plan level, not the brand level. Two neighbors with the same insurer can have entirely different hearing benefits.
"No benefit means full price." FSA and HSA dollars, financing, and honest tier-matching routinely bring the real cost well below the sticker number.
"The covered option is always the cheapest." Allowances tied to catalogs can steer you toward a device that fits the program better than it fits you. Compare the five-year picture, not the first receipt.
References
- Centers for Medicare & Medicaid Services. "Hearing Aid Coverage." Medicare.gov. Accessed 2026.
- Centers for Medicare & Medicaid Services. "Hearing & Balance Exams." Medicare.gov. Accessed 2026.
- KFF (Kaiser Family Foundation). (2025). "Medicare Advantage 2025: Extra Benefits, including Hearing." kff.org.
- National Council on Aging. "Does Medicare Cover Hearing Aids?" ncoa.org.
- New York State Department of Financial Services. Consumer guidance on health insurance coverage. dfs.ny.gov.
About the reviewer: Dr. Eric G. Nelson, Au.D., CCC-A, is a board certified Doctor of Audiology, founder and clinical director of Pinnacle Audiology, and a former audiology supervisor at Weill Cornell Medicine. This article is educational and does not guarantee coverage; benefits are confirmed through plan verification.
Get expert
hearing care.
Comprehensive evaluation, honest guidance, and long-term support, from New York's leading independent audiology practice.